Introduktion
Unlocking the Next Wave of Growth
The Stockholm momentum
»Stockholm has something that many other cities are trying to build but few manage to create: a unique combination of technical expertise, entrepreneurial spirit, high quality of life, and trust.«
Stockholm is often described as one of Europe’s best-functioning and most beautiful cities. However, over the past three decades, Stockholm has built something considerably more remarkable than a beautiful city. Here, one of the world’s most successful tech ecosystems has taken shape and is on track to lead Europe into the next era of digital innovation if we leverage our strengths correctly.
From Spotify and Klarna to the latest generation of fast-growing companies in AI, fintech, game development, and life sciences, Stockholm has repeatedly demonstrated an ability to create companies that reach far beyond our borders. With a population smaller than some of Europe’s largest metropolitan regions, we play a disproportionately large role in global technological development. Our companies compete on the world market. Our innovations are used by hundreds of millions of people every day. Stockholm has become a place where entrepreneurs, investors, and talent come to build the next generation of companies.
When we began work on this report, we started like many others, with a sense that Stockholm still has much work to do. Public debate is often shaped by stories about crime, housing shortages, skills gaps, and inadequate infrastructure. These challenges are real and must be taken with the utmost seriousness. But as we began to study the facts, a different picture emerged.
Our startup scene is thriving, venture capital continues to flow here, and universities and research institutions maintain a high international standard. At the same time, it would be a mistake to take today’s position for granted. In a world where competition for talent intensifies every year, cities are no longer competing only for investment and company relocations. They are competing for the individuals who turn knowledge into innovation and build the companies of the future. It is here that challenges remain.
An international entrepreneur looking to establish themselves in Stockholm still faces long processing times. Companies report difficulties recruiting top talent from other countries. The housing market does not function as it should. Arlanda’s international connectivity has weakened. Meanwhile, development is moving fast in cities like Amsterdam, London, Berlin, and Copenhagen, all competing for the same people we are.
That is precisely why this report is not simply about describing successes. It is about understanding what has made Stockholm successful, and what is required for us to remain so, because there is every reason for confidence in the future. Stockholm has something that many other cities are trying to build but few manage to create: a unique combination of technical expertise, entrepreneurial spirit, high quality of life, and trust. That is a strong foundation to stand on, but tomorrow’s position must be earned.
If Stockholm is to remain one of the world’s leading tech cities, we need to attract more talent, retain more companies, and create even better conditions for people to live, work, and develop their ideas here.

Daniella Waldfogel
vd, Stockholms Handelskammare
Report in 3 minutes
Stockholm is one of Europe’s leading tech and innovation hubs. World-class universities, a dense startup ecosystem, strong VC activity, and a global reputation for sustainability and product excellence set it apart from many of its competitors.
However, to maintain this lead, Sweden must urgently resolve three critical bottlenecks:
▶ Talent Attraction
Long processing times and a lack of transparency have led to waiting in limbo and a high rejection rate, particularly for Sweden’s residence permit for self-employment (egenföretagare), the closest equivalent of a startup or entrepreneur visa.
- Over the past five years, the average processing time for the permit was 16 months, nearly a year and a half.
- That is eight times the two-month average across 13 comparable European countries.
- Only 7% of applications were accepted in 2025.
▶ Employee incentives
The structure of one of Sweden’s most important tools for attracting talent to startups and scaleups, Qualified Employee Stock Options (QESOs), needs to be recalibrated for today’s high-growth companies.
- Among Stockholm-headquartered startups and scaleups founded in the past 10 years, 9% do not qualify for QESOs.
- Those unqualified companies account for 92% of the cohort’s annual revenue and 60% of the jobs it has created.
▶ Late-stage capital
Sweden has a strong early-stage ecosystem in which many ideas are able to grow into companies. At critical growth stages, however, domestic capital is too scarce to scale them further, pushing founders to seek funding abroad.
- Stockholm ranks third among European metro regions for most total venture capital (VC) raised over the last 12 months (Q2 2025–Q2 2026), with estimates of roughly 66% coming from outside of Sweden.
- Stockholm ranks fifth in Europe as a hub for deep tech, while at the same time deep tech funding fell by 82% between 2020 and 2025, the steepest decline of any European hub.
Stockholm: From legacy to leadership
Stockholm has long been a city where innovation meets entrepreneurship. A foundation of trust and equality, combined with an open, global outlook, fuels the ambition that drives it forward. The result is an environment that has produced some of the world’s most successful companies, a trend that continues today.
The world’s fastest-growing software company ever, Lovable, along with Legora, another of Europe’s fastest-growing companies, are just two standout examples of what has come out of Stockholm in recent years. At the same time, Stockholm has become Europe’s top IPO hub in 2025, ranking fifth globally and hosting four of the continent’s ten biggest listings.1 Attitudes among investors, entrepreneurs, researchers, and the wider business community point in the same direction.
As a relatively small city on the northern fringes of Europe, Stockholm is not the likeliest candidate to become one of the continent’s strongest tech hubs. Yet that is perhaps exactly why it has. Cities such as London and Paris operate at a larger scale, with deeper talent pools and greater access to capital; companies founded in Stockholm must think globally from day one. That means being more flexible, more open for business, and more international than the competition, and always looking beyond Sweden’s borders.
The tech sector exemplifies this way of building and will be this report’s focus as we highlight what must change to accommodate the next wave of innovation.
A history of innovation, a culture of doers
Sweden’s reputation as an innovation nation is not a recent invention but the product of nearly 150 years of inventive industry. Alfred Nobel’s patent for dynamite in 1867 stands as one of the defining contributions of this era, a period of remarkable industrial invention that would reshape the modern world. Of the 355 patents over his lifetime, this invention would go on to revolutionise mining, tunnelling, quarrying and other large-scale construction critical to global infrastructure development. Less than a decade later, in 1876, Lars Magnus Ericsson opened a small telegraph repair workshop in Stockholm that would eventually grow into Ericsson, one of the world’s dominant telecommunications equipment makers and a central force in the global rollout of mobile networks to this day.
The twentieth century saw Sweden’s innovativeness continue with a remarkable cluster of globally significant companies produced. SKF, founded in Gothenburg in 1907, invented the self-aligning ball bearing, becoming fundamental to virtually every vehicle, factory, and piece of industrial equipment in the modern world. Astra AB was founded in 1913, producing landmark drugs for years before merging with Britain’s Zeneca in 1999 to form the modern company AstraZeneca, that notably co-developed one of the first widely deployed COVID-19 vaccines with Oxford University. IKEA, founded by Ingvar Kamprad in 1943, reinvented how furniture is distributed and sold through flat-pack design and self-assembly, becoming the world’s largest furniture retailer. Tetra Pak, founded by Ruben Rausing in Lund in 1951, revolutionised food distribution with its aseptic carton packaging, allowing perishables to be stored for months without refrigeration.
Taken together, these companies illustrate a recurring Swedish pattern of turning a focused technical insight into a globally scaled business that punches far beyond what a country that today numbers roughly ten million people would be expected to produce. The last 30 years have seen that same instinct translate into a new domain, one where success has come from building solutions without waiting for permission. Early investment in broadband and digital literacy in the 1990s left Sweden unusually well-prepared for the internet age. Combined with a culture of engineering excellence and a mostly hands-off government, it created the space for anyone to build.
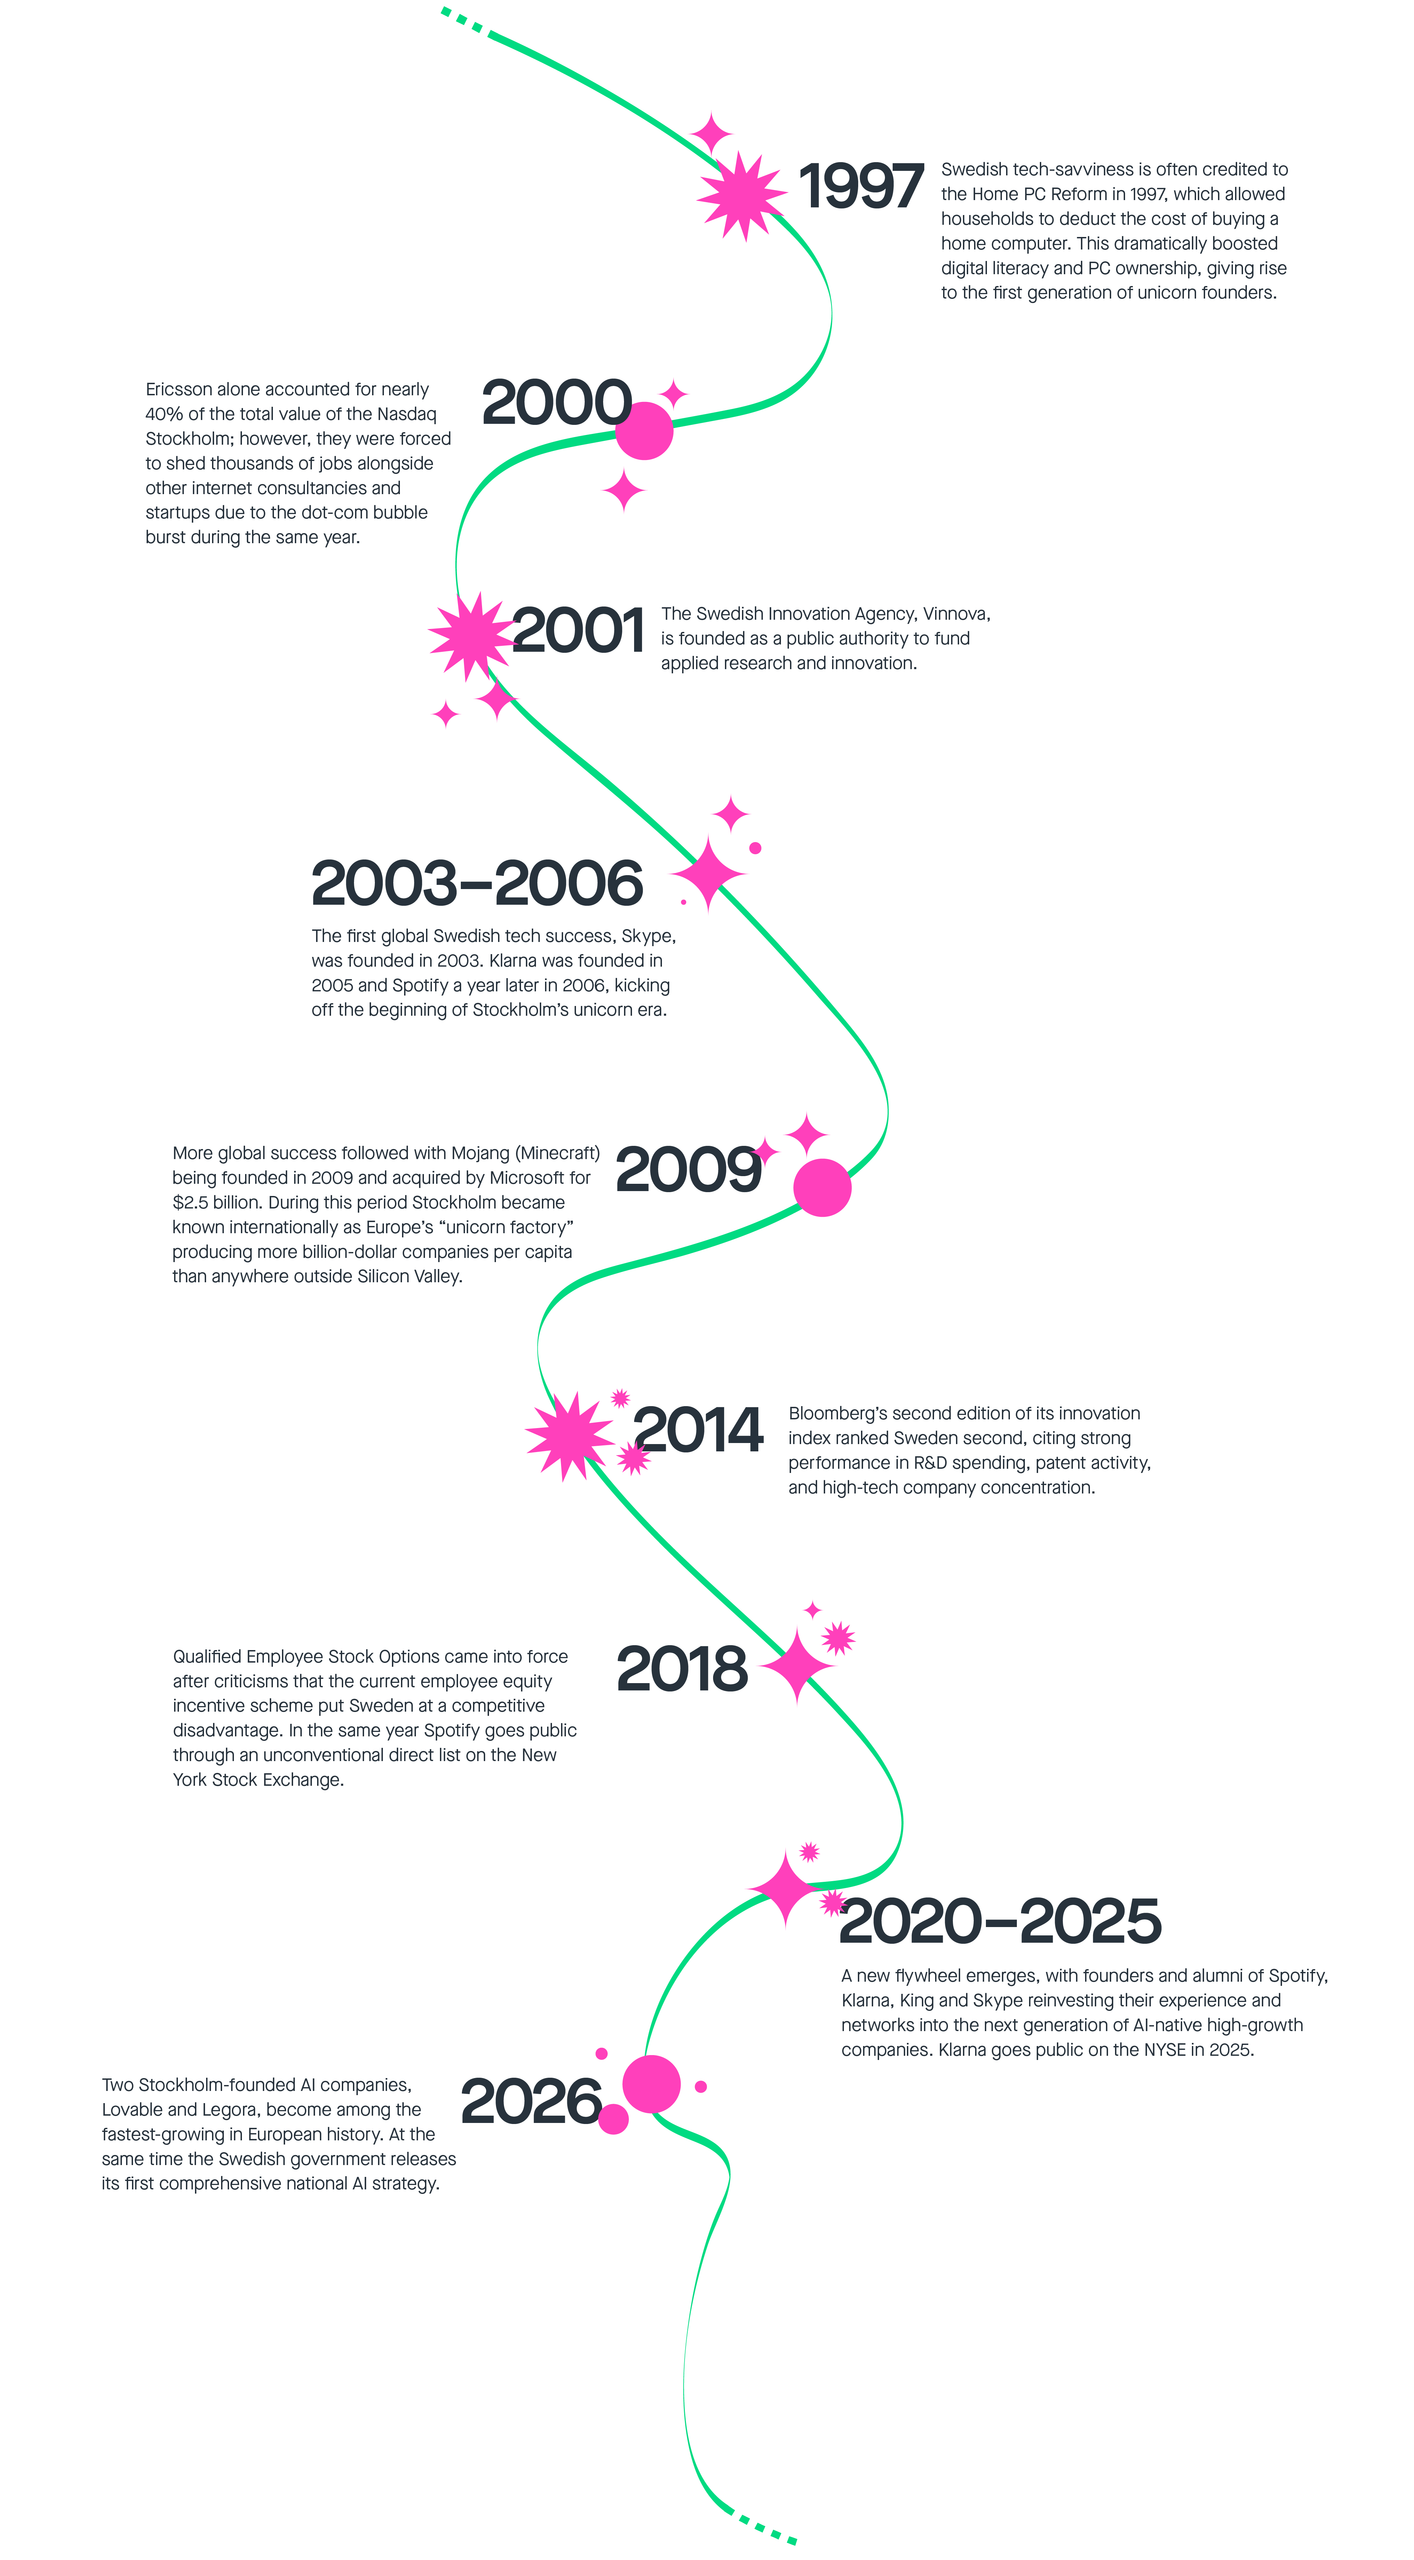
What we see today is the result of a cultural flywheel set in motion three decades ago, now reinvesting back into today’s tech sector. Experienced founders and established companies help the next cohort navigate building in Sweden and scaling beyond, while up-and-comers bring fresh ways of working and new technologies in return. This sense of community, combined with a foundation of trust built up over decades of measured, responsible progress, is what has compounded into the positive outlook and global positioning Stockholm enjoys today.
Delivering at a global level
As mentioned, Stockholm’s current standing is the product of culture and key industry moments compounded over years. While not necessarily known for developing novel technologies, the ecosystem excels at applying them to create strong, scalable products, particularly when it comes to product design, user experience and a deep understanding of customer needs. Spotify and Klarna illustrate this well, alongside newer players like Lovable and Legora, proving that globally competitive companies can emerge outside the Bay Area.
Another defining feature is the density of the ecosystem itself. Founders, investors, and talent operate in close proximity, sharing ideas easily and often. This is reinforced by a strong ”founder factory” culture, where alumni from successful startups go on to launch new ventures or become early-stage investors, creating a continuous recycling of talent, experience and capital.
Sweden’s culture of active ownership adds another distinctive layer. Unlike in many other markets, capital is not concentrated solely among institutional investors but widely distributed across society. Nearly half of Swedish households invest in equities or funds, contributing to a high level of engagement in the capital market and a long-term investment mindset. Combined with strong institutional investors, this creates a close bond between founders, investors and society at large.
Together, these factors create an environment where capital, talent and knowledge circulate freely. Combined with the international credibility that comes from being a Swedish-founded company, it becomes natural to think globally and plan for international expansion from day one.
| Company | Founded companies |
|---|---|
| Klarna | 75 |
| Spotify | 67 |
| Revolut | 58 |
| Deliveroo | 57 |
| King | 55 |
| Zalando | 54 |
| Criteo | 53 |
| Delivery Hero | 42 |
| Wix | 37 |
| N26 | 36 |
Source: Dealroom, 2026
-
Stockholm generated 43% of Sweden’s economic growth over 20 years with only 25% of the workforce.
-
The Stockholm Stock Exchange accounted for 60% of total IPO transaction volume in Europe in 2025 and four of the ten largest IPOs.
-
Stockholm ranks 3rd in Europe for VC raised over the last year (Q2 2025–Q2 2026), signalling a strong ecosystem for attracting investment.
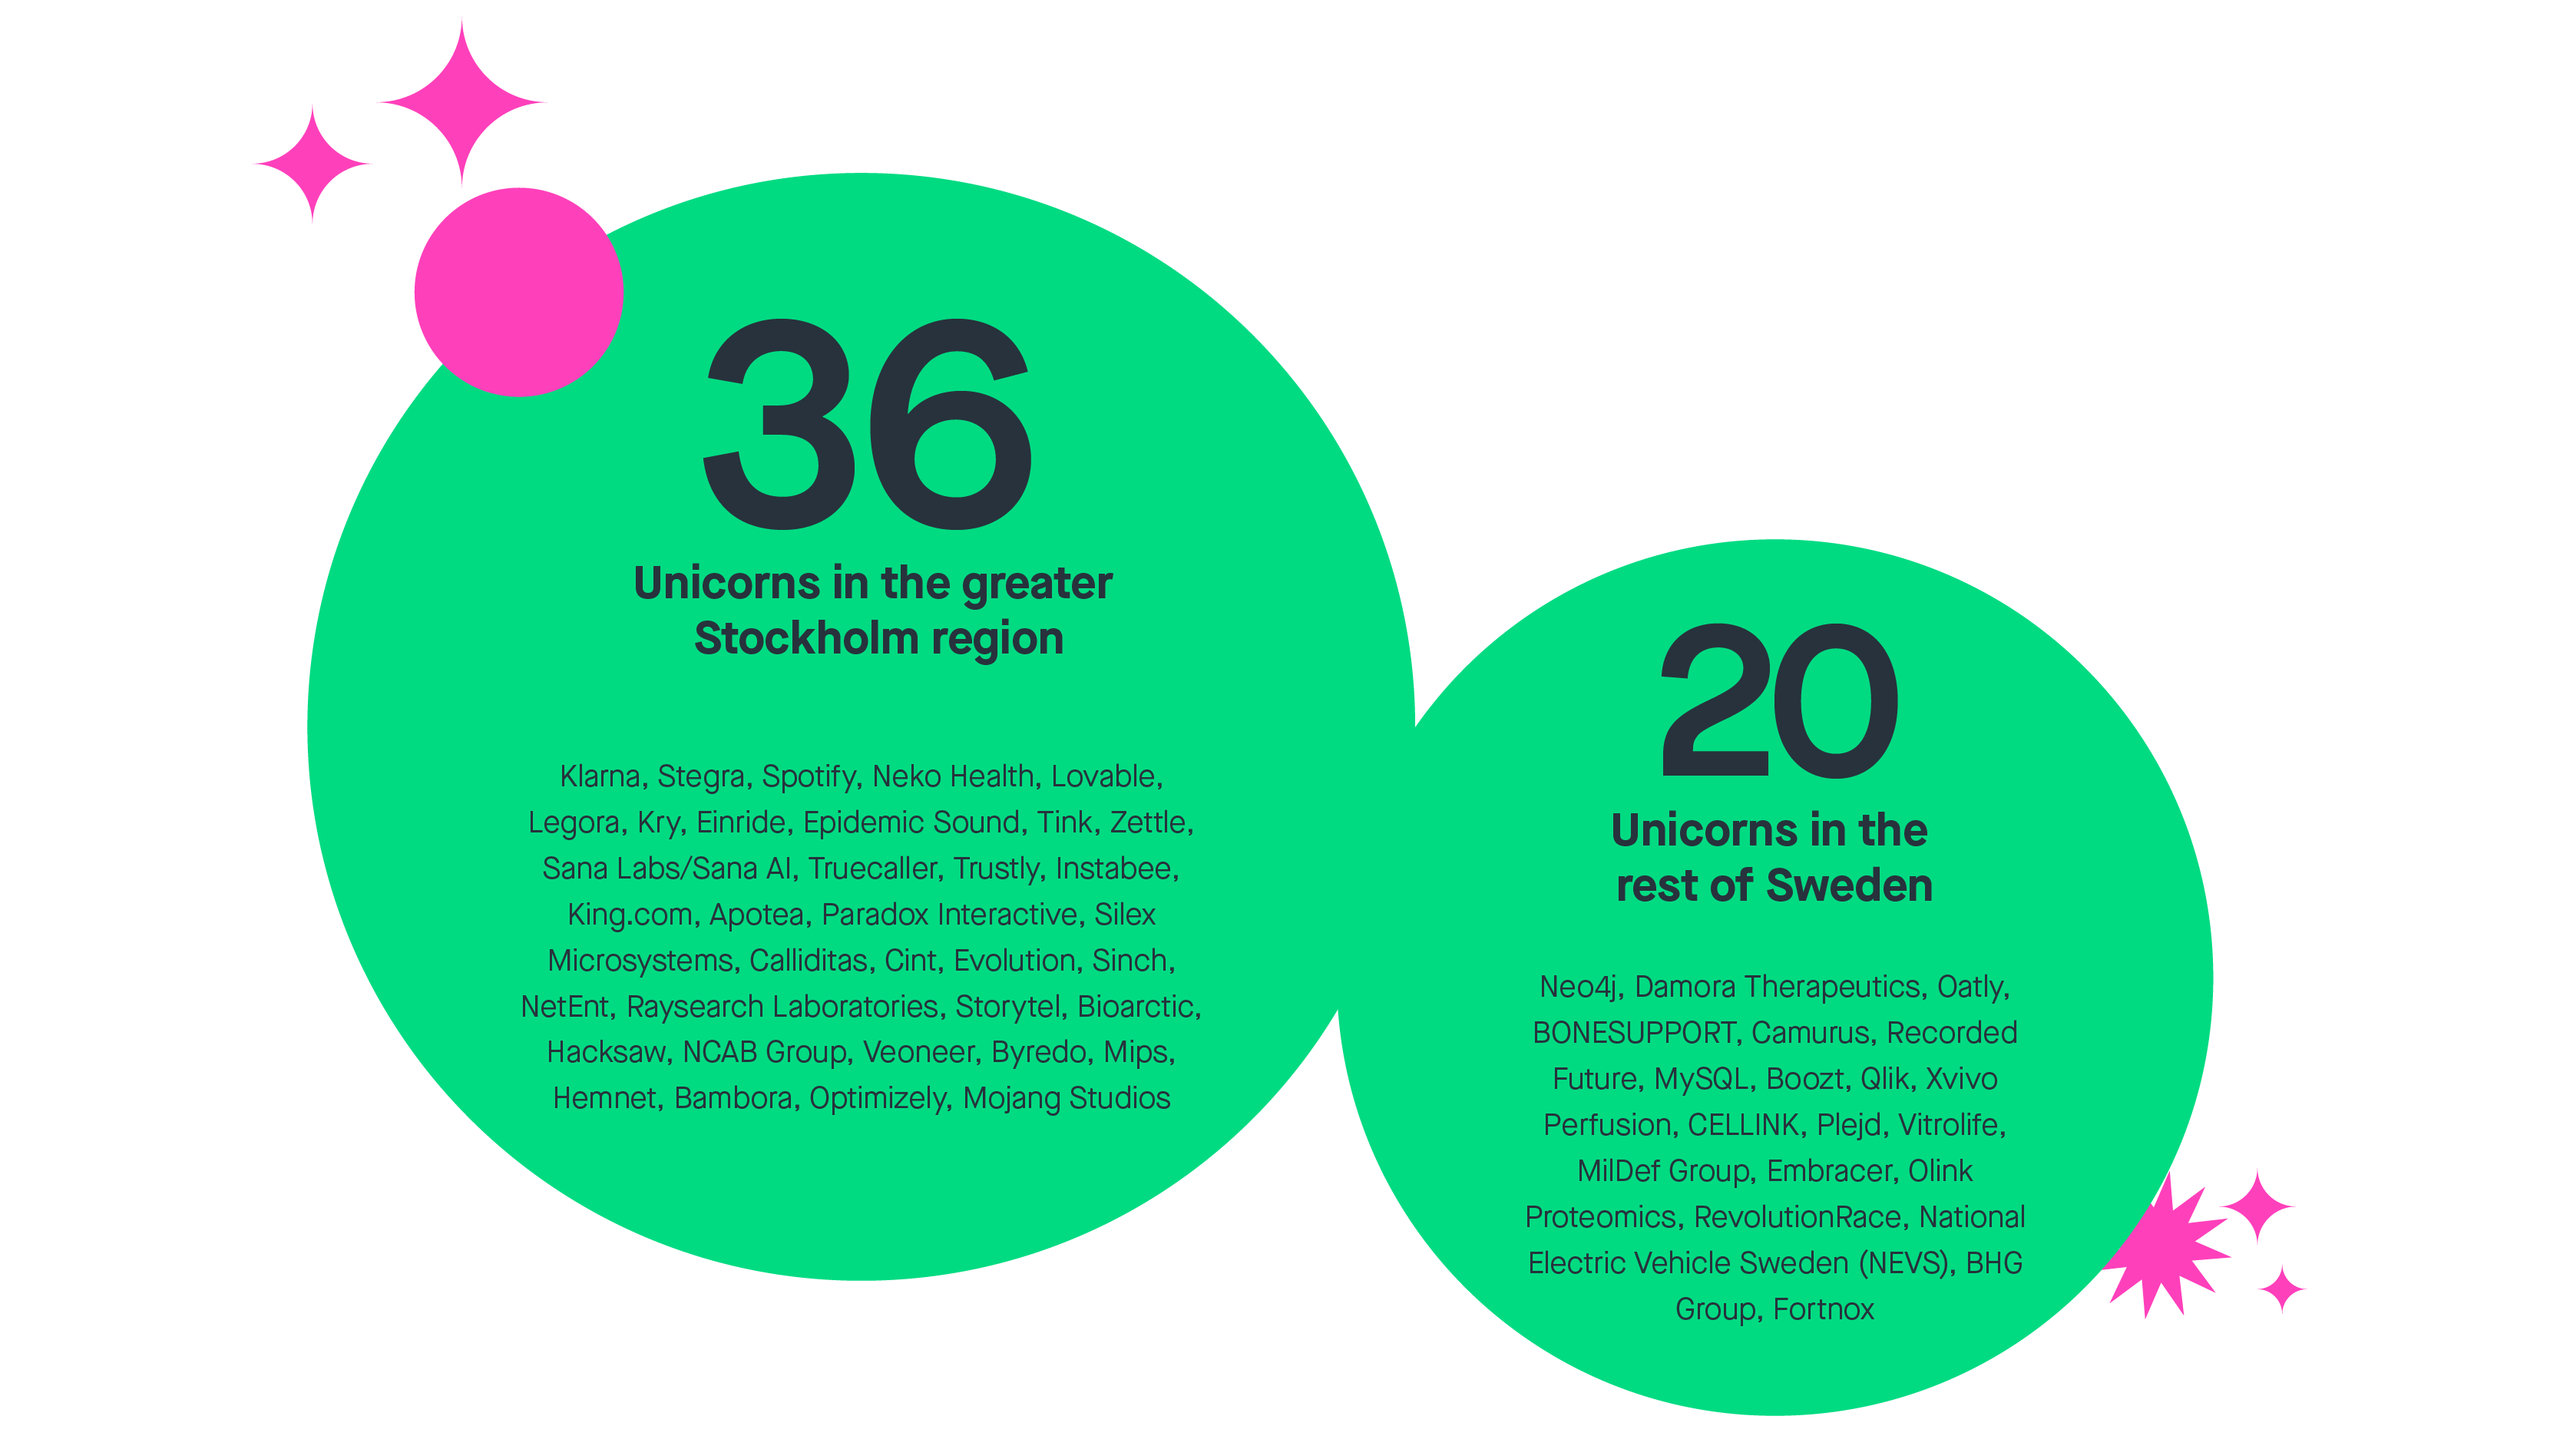
Sweden has a total of 56 unicorns
Including both companies independent today and ones later acquired or exited. Stockholm alone has more unicorns per capita than New York, Los Angeles, or London with 36 produced in total.
| Company | Valuation (SEK billion) | Sector | Last round |
|---|---|---|---|
| Lovable | 126.3 | AI coding platform | Series C (August 2026) |
| Neko Health | 66.5 | AI health scanning | Series C (July 2026) |
| Legora | 52.7 | Legal AI | Series D (March 2026) |
| Kry/Livi | 19 | Digital healthcare | Series D (2021) |
| Epidemic Sound | 13.3 | Music Licensing | (2025) |
Source: Dealroom
Spinout success
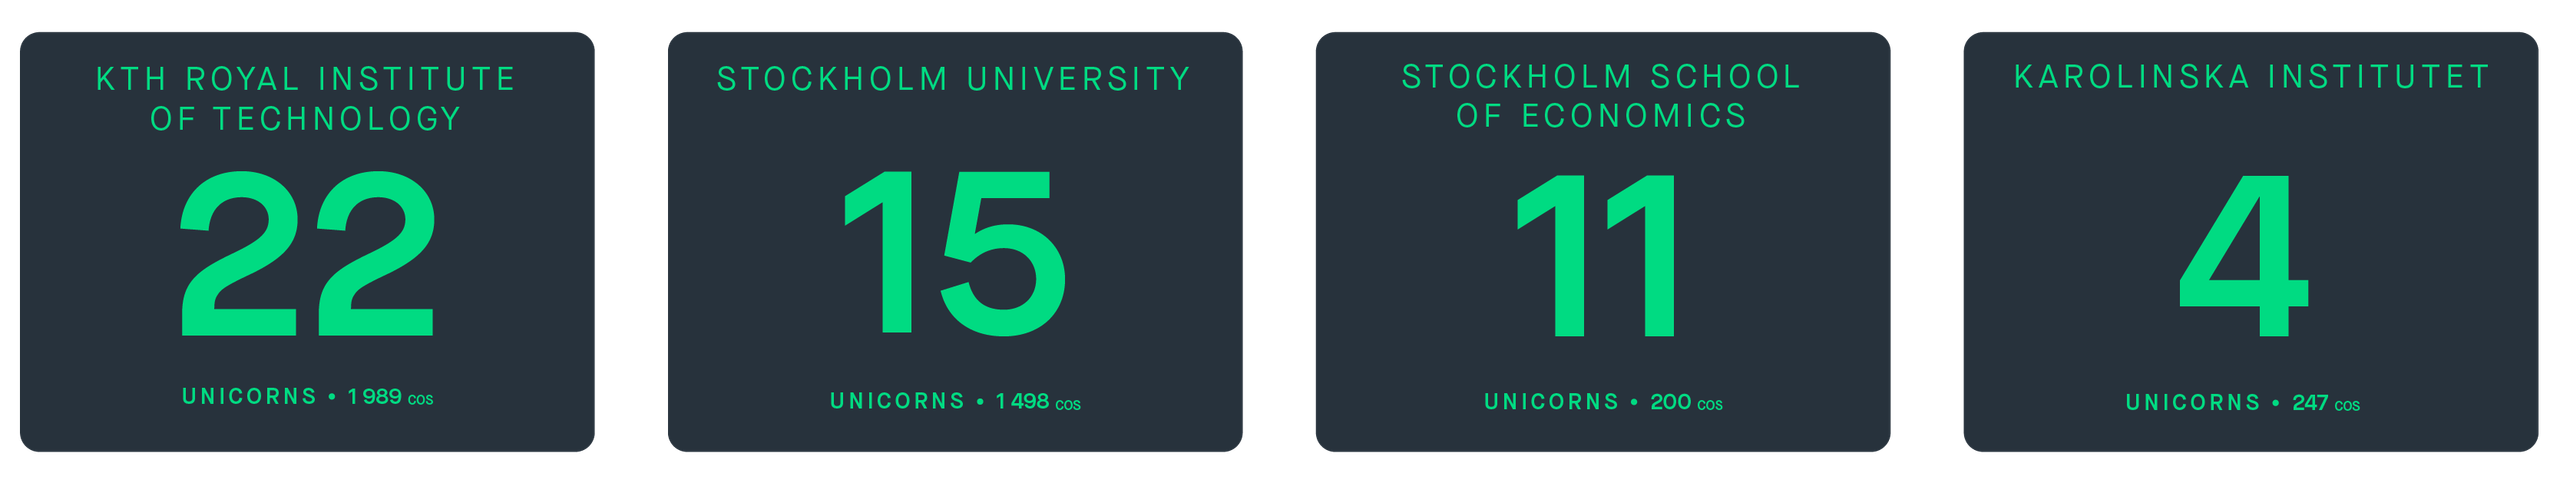
Stockholm’s universities are leading in creating startups and spinout value. KTH ranks number 3 in Europe for the greatest number of spinouts (270) behind HEC Paris (1509) and Technical University of Denmark (309) (Dealroom). A spinout is categorised as a company that commercialises intellectual property developed at a university or research institution.
Global tech rankings
In the Global Tech Ecosystem Index 2026, Stockholm ranks number 3 in Europe and within the top 20 tech hubs in the world. More notably Stockholm ranks number 8 globally and first in the EU among the world’s densest tech ecosystems. (Dealroom, 2026)
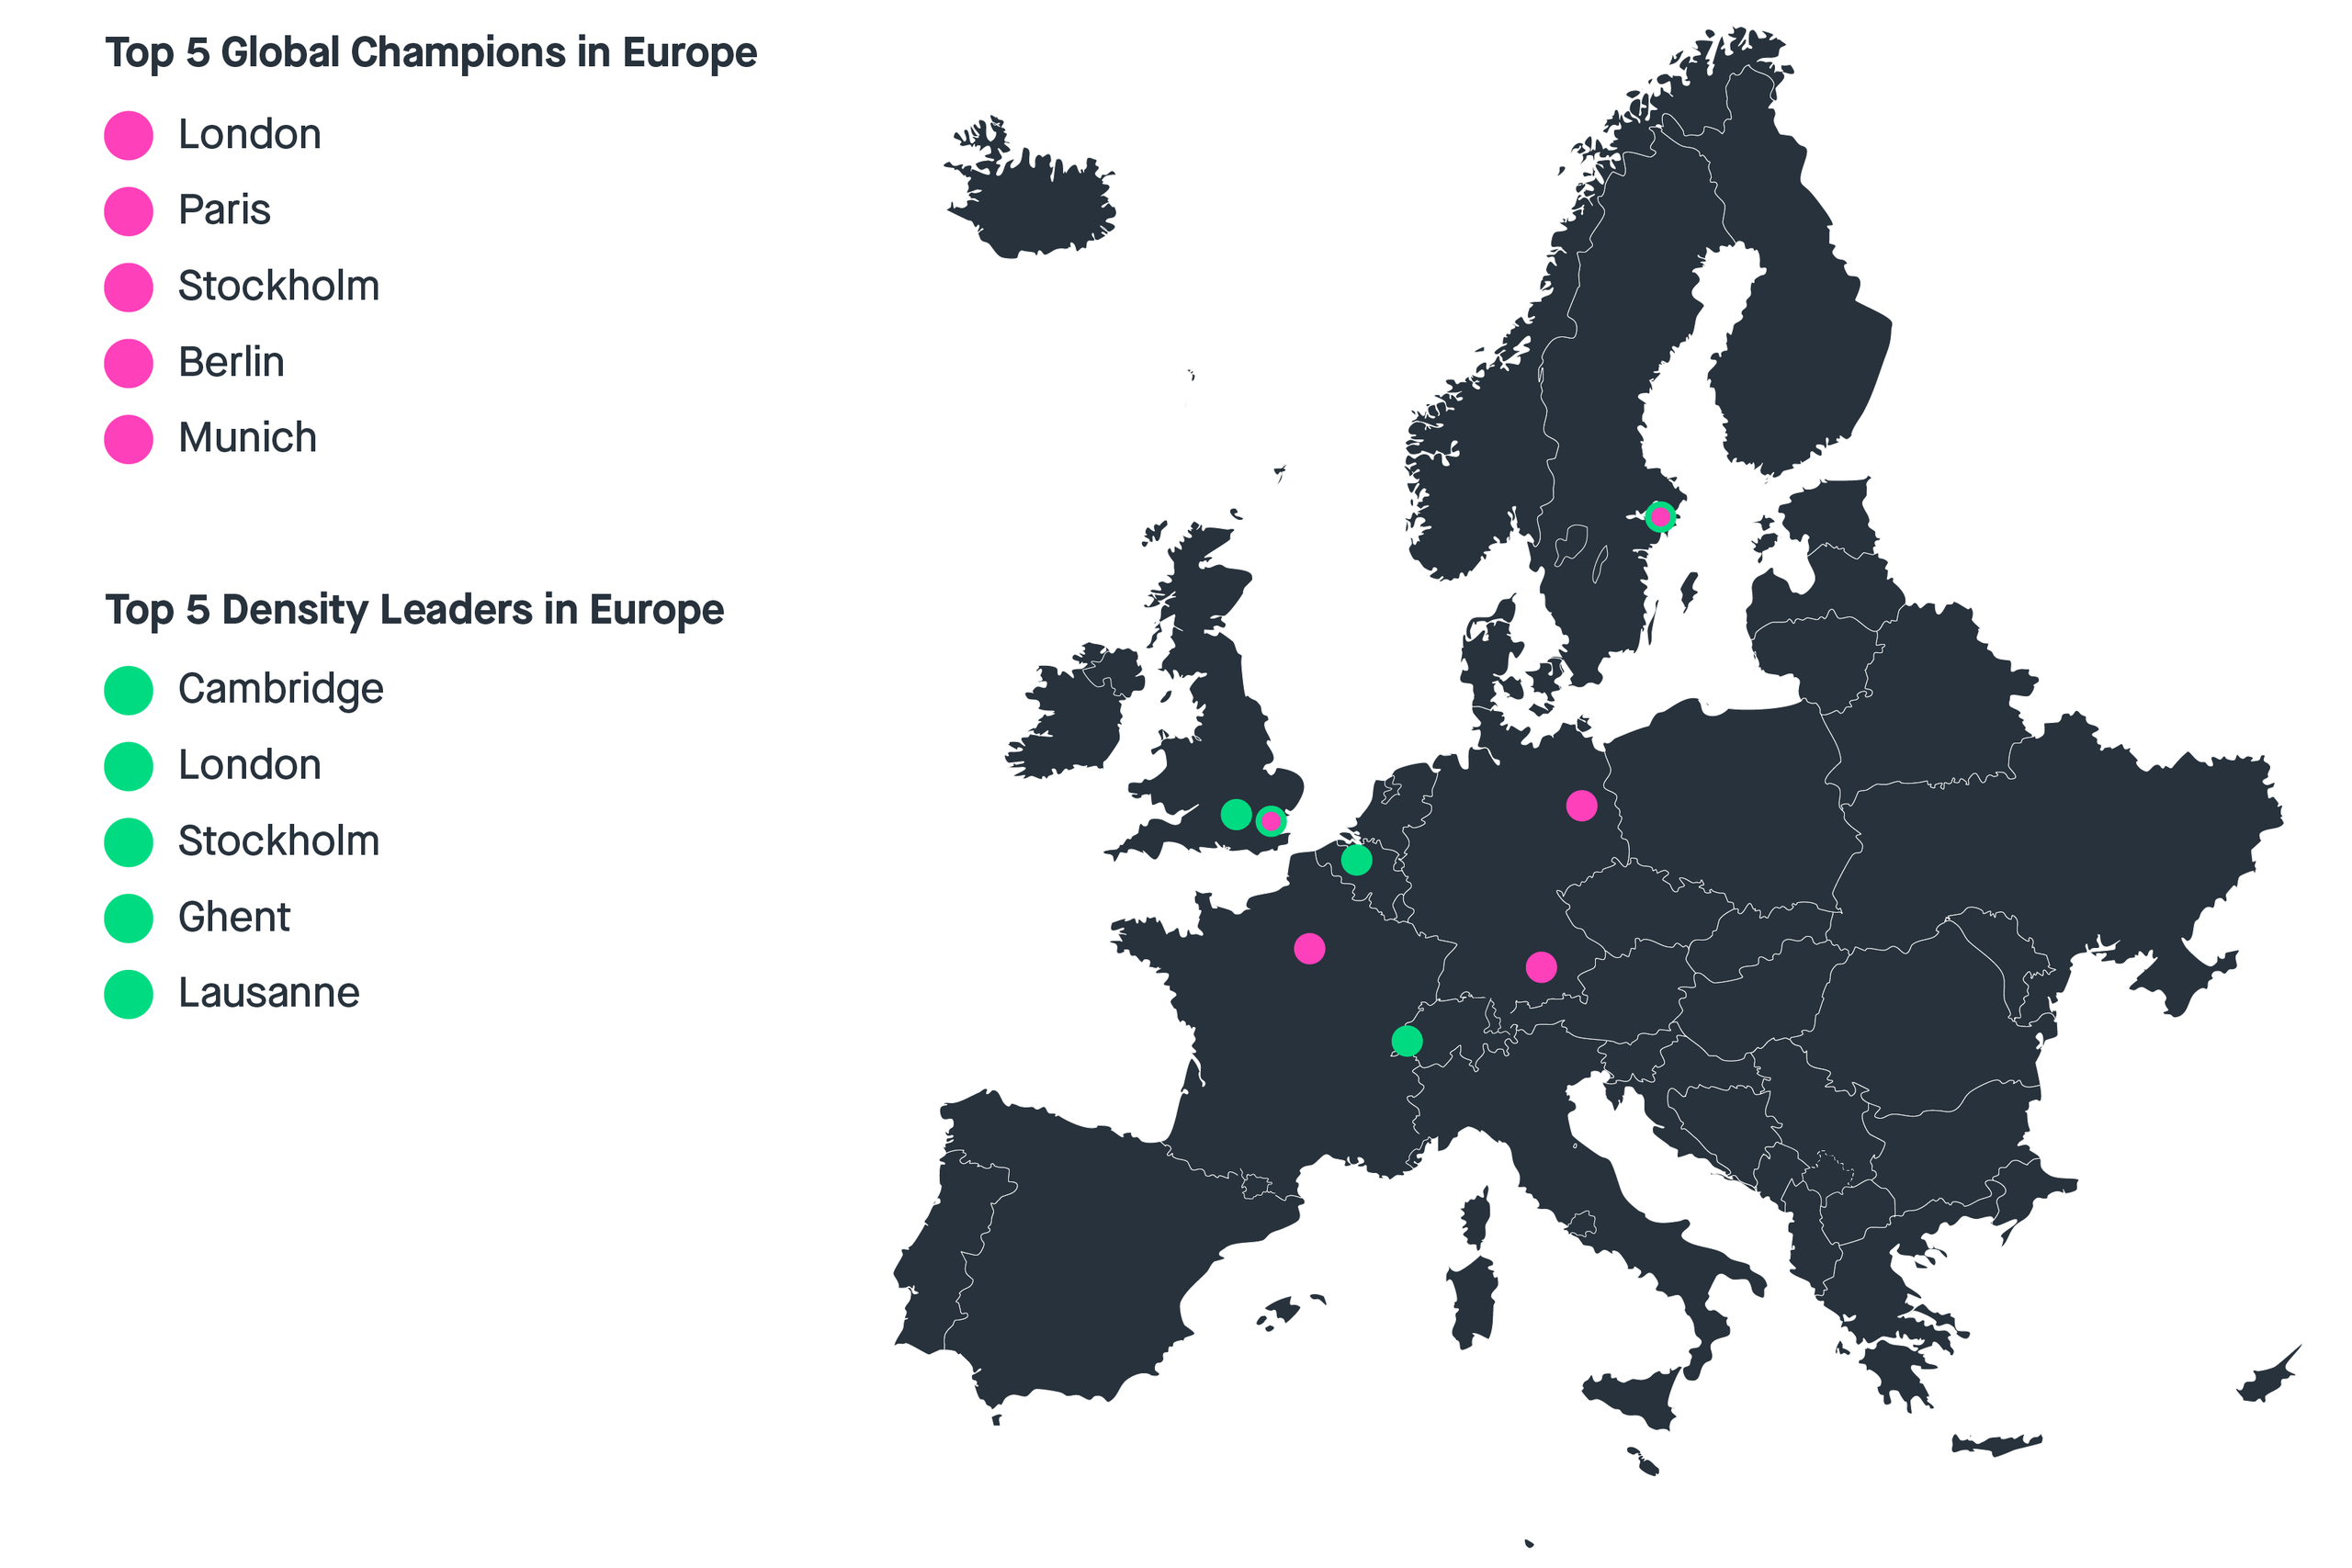
Beyond just tech, Stockholm is Europe’s most innovative region, ahead of cities such as Copenhagen, London, and Zurich, reflecting strengths in human capital, research, and business innovation.2 In practice, this means that the region combines a highly skilled workforce with the ability to turn research into commercial success.
At the national level, Sweden ranks second globally for innovation and fifth for talent competitiveness.3 4 Sweden also has the highest share of information and communications technology (ICT) specialists in the EU, indicating a workforce with advanced technical skills.5 At the same time, research and development (R&D) investment accounts for 3.6% of GDP, well above the EU average of 2.2%, placing Sweden among the top global investors in innovation.6 Together, these factors point to an economy built on knowledge-intensive and technology-driven industries, forming the foundation of Stockholm’s competitiveness and success.
Taking the next step
Stockholm clearly has a lot going for it. World-class founders, talent, and investors have created the strong ecosystem we see today and will no doubt continue to attract more people and capital as the years go on. However, if Sweden falls behind technologically or becomes harder to build in, then we are faced with the possibility of losing our current momentum. To keep this strong standing and continue to deliver at a global level select areas will need to be more strategically assessed in the coming years.
Embracing AI
AI is a critical part of this story and Sweden is quickly becoming an AI-native hub, both in Europe and on the global stage. However, with technology moving this fast, a slow approach risks us falling behind. Adoption is the clearest example and without intent from both the public and private side, Sweden’s future digital development could be set back significantly. This urgency was raised by the government-backed AI Commission led by Carl-Henric Svanberg, whose report, pointedly released ahead of schedule in November 2024, signalled that Sweden needs to move faster. Its recommendations focused on political leadership in the form of a national strategy, a centralised task force, and an ”AI for all” reform, alongside dedicated investment in education, research, and innovation.
The response came in two parts. In May 2025, the Swedish AI Reform was announced, launched by the Swedish AI Reform Foundation in collaboration with Sana Labs and backed by Prime Minister Ulf Kristersson. While not a government reform in the traditional sense, it seeks to build on the success of the 1990s Home-PC reform, giving civil servants, teachers, students over the age of 13, researchers, and non-profit employees free access to civic tier Sana Agents, allowing them to build custom AI agents trained on their own institutional data to automate tasks and boost productivity. Roughly half a year later, in February 2026, Sweden’s national AI strategy was presented. While the long-awaited release was welcomed, it was also widely criticised for not being ambitious enough.
This critique reflects a long-standing concern that Sweden has been too slow to adopt and apply AI at a national level. It points to a lack of strategic investment from Swedish companies and authorities, a risk-averse culture weighed down by regulatory burden, and a cautious government. Private companies, by contrast, have moved much faster, often with little direction from the public side. The result is a mixed picture with Sweden already home to some of the world’s most innovative and fastest-growing AI-native companies, yet wider adoption, integration, and education around AI as a tool all lag.
AI adoption in Sweden lags behind that of the US
Figure 1. Share of workers using generative AI in 2026
Source: Brookings, 2026
Part of the slowness is structural. Sweden does not have a standalone AI law and is instead implementing the EU AI Act, which became fully applicable on 2 August 2026, with bans on unacceptable-risk systems already in effect since February 2025. In October 2025, the government proposed complementary legislation (SOU 2025:101) designating the Swedish Post and Telecom Authority (Post- och telestyrelsen) as the main market surveillance authority, alongside eleven sectoral bodies. The framework is understandable, however parts of the Swedish tech community worry that complex, risk-based rules, combined with a national strategy more cautious than ambitious, risks leaving Sweden and Europe trailing the United States and China, where lighter regulation and deeper capital pools continue to pull talent and companies away.
Top founders have also criticised the amount pledged by the government as barely enough to fund a startup’s Series A round, far short of what a national strategy demands.7 This lack of ambition could have damaging consequences down the line, especially as Sweden looks to position itself as an AI hub. Left unaddressed, these doubts compound, sending a message to the world that things are good here, but not good enough. Sweden has signalled that it is ready for the next step and has attracted significant investment already, but staying competitive will require a more collective effort across the public and private sectors.
Staying competitive
AI is just one area where more attention is needed but will not be the primary focus of this report. Instead, we turn to a set of specific challenges emerging as potential barriers to Sweden’s continued growth and standing as one of Europe’s leading tech hubs: migration policy for high-skilled workers from outside the EU, employee tax incentives that remain too rigid for today’s high-growth companies, and capital for late-stage funding that keeps companies in Sweden as they scale.
While these challenges and the recommendations that follow are not unique to tech, the sector will run through this report as both example and opportunity. Tech firms are less tied to geography than most other industries, and when conditions turn unfavourable, they are able to relocate more easily than most, making them an early indicator of broader competitiveness. The challenges, however, apply to a much wider segment of the business community contributing to the Stockholm region’s strength.
The structural question is whether Sweden can grow with the momentum Stockholm is generating right now. If we cannot meet the demands of fast-scaling companies, we risk losing them. Therefore, the remainder of this report explores the identified three areas and targeted reform strategies which could have a significant impact on the continued growth of new and scaling companies, including:
-
Attracting talent through key migration reforms
Today this process is too slow and bureaucratic for it to be competitive amongst the rest of Europe.
-
Improving critical employee incentives
While Qualified Employee Stock Options (QESOs) are a step in the right direction, they need to be adapted to today’s high-growth companies and simplified so that more companies can implement them.
-
Capital deployment at scale
American funding in growth stages is common, however there is under-utilised pension and government capital in Sweden that could be unlocked.
Interview: Stockholm’s success story
Spotify is the canonical example of how great product design and user experience can win a global market. It has long since outgrown Sweden, but Stockholm remains part of its DNA.
Arvid Hedman, VP Employee Experience at Spotify
What has surprised you most over the last 10 years in terms of Spotify’s growth and development?
“The global expansion has been the most striking thing to witness. When I think back over the last decade, the scale of what we’ve built outside Sweden is remarkable, and yet our executive team is still largely based here in Stockholm, which I find impressive. The other shift has been how much the centre of gravity for our workforce has moved to the US, driven by a more liquid talent pool with faster turnover and broader availability, which has reshaped what Spotify looks like as a company in ways I wouldn’t have predicted ten years ago.”
How important is Stockholm and its recent tech successes for Spotify?
“Stockholm remains important to us, and the current wave of tech success in the city is genuinely good for everyone. Stockholm’s success is shared, and we’re seeing real momentum in AI talent being drawn to Sweden as a result. As one of Stockholm’s success stories, we feel an obligation to take the meetings, share what we’ve learned, and help the next generation avoid the mistakes we made, which only makes Stockholm a more compelling place for us to be.”
- 1 https://cryptorank.io/news/feed/e05fa-stockholm-europe-top-ipo-destination (länk)
- 2 https://research-and-innovation.ec.europa.eu/statistics/performance-indicators/european-innovation-scoreboard_en (länk)
- 3 https://www.wipo.int/web-publications/global-innovation-index-2025/en/index.html (länk)
- 4 https://knowledge.insead.edu/strategy/worlds-most-talent-competitive-countries-2025 (länk)
- 5 https://ec.europa.eu/eurostat/web/interactive-%20publications/digitalisation-2025#digital-skills (länk)
- 6 https://ec.europa.eu/eurostat/statistics-explained/index.php?title=R%26D_expenditure (länk)
- 7 https://sifted.eu/articles/swedens-ai-strategy-wont-keep-its-best-founders-at-home (länk)
A closed door in an open economy
The hidden costs of Sweden’s migration system
As a knowledge-based economy, Stockholm and Sweden need to be able to attract and bring on board highly skilled individuals from abroad, especially outside the EU. The table below shows the proportion of accepted applications for highly skilled labour immigration (specifically pertaining to the standard work visa), which over the period from 2021–2025 was 51% on average. This reveals that on average just over half of Sweden’s labour immigration falls into the highly skilled category. If we are to keep this up and stay competitive, we need to address some key structural challenges that are impacting the system as it looks today.
Figure 2. Approved work permits to Sweden
Source: Swedish Migration Agency
To provide an overview of the state of today’s system, three different types of visas that specifically target non-EU citizens applying from outside of Sweden were investigated based on uptake, acceptance rates, and processing times. Firstly, the residence permit for self-employment (egenföretagare) which is the closest solution Sweden has to a startup or founder’s visa. This visa is aimed at those either planning to run their own company in Sweden, take over an existing Swedish company, or work as a sole proprietor. Key conditions include 51% ownership of the business, SEK 200,000 capital up front, plus an additional SEK 100,000 for a spouse and SEK 50,000 per child where applicable. Proof of a customer network in Sweden, and previous experience running a business are also necessary, alongside enough funds to sustain the proposed business. There is no exact amount listed for business funds, likely because this depends on the nature of the business and is evaluated during the application process.
The second visa investigated was one of three higher education visas which applies to those who are looking for work or to start their own business (söka arbete eller starta verksamhet) specifically coming from outside the EU. Introduced in 2022, this is a temporary and non-renewable residence permit that allows people with a completed university degree at a master’s level or higher to enter Sweden for a period of 3-9 months.
Lastly, we looked at the standard work visa (arbetstagare), for those that have received a job offer from a Swedish company to come work in Sweden.
Over the last six years 3,509 applications have been received for the residence permit for self-employment, 7,216 for the higher education visa, and 143,038 for the work visa. Since the peak of applications in 2022 there has been a steady decline with the total number of applications for all three visas decreasing by 51% between 2022 and 2025.
Figure 3. Number of residence permit applications received
Source: Swedish Migration Agency
One possible answer to this sharp decline could be due to processing times. The average processing time over the last six years for the residence permit for self-employment comes in at 16 months, which, while shorter than the Migration Agency’s own prediction of 18-24 months, is a staggering amount of time. The higher education visa comes in at seven months of processing time, and the work visa averages four months.
Figure 4. Average processing time by residence permit type
Months, dotted line represents one year
Source: Swedish Migration Agency
The residence permit for self-employment processing time averaging 16 months sends a clear message to founders looking at Sweden as a potential option. Those with growing companies typically do not have this kind of time to wait for a decision. Industry data shows the average time from initial idea to Series A funding is approximately 2.5 years for successful startups, meaning this kind of wait consumes over half the critical window before a founder can really begin.8 To contextualise the problem even more, Sweden’s closest competitors across Europe were compiled to compare predicted, average processing times for equivalent startup visas. Across these 13 other countries (shown in Figure 2.4) the average processing time for a startup-visa was 2 months, 8 times faster than Sweden’s residence permit for self-employment at 16 months.
Figure 5. Visa processing times across Europe
Months, dotted line represents one year
Lastly, we considered the acceptance rates for each type of visa we analysed, and again the results show a clear problem. In 2025, only 7% of applications for the residence permit for self-employment were accepted. For the highly educated visa 12% were accepted, and 57% for the work visa.
Figure 6. Number of settled and approved cases relating to the residence permit for self-employment
Source: Swedish Migration Agency
Figure 7. Number of settled and approved cases relating to the residence permit to look for work or start a business
Source: Swedish Migration Agency
In terms of the residence permit for self-employment, most rational founders would not wait 1.5 years for a visa with a 93% likelihood their application will be rejected. At the same time there is a 76% increase in applications in 2025, which could signal an increased interest in starting or leading a company in Sweden. This can be interpreted as a critical point in time where despite long process times and high rejection rates people still see the value in Sweden.
Figure 8. Number of settled and approved cases relating to the residence permit for employment by a Swedish company
Source: Swedish Migration Agency
While the processing times are problematic, many of the conditions for the residence permit for self-employment also do not reflect how entrepreneurship works today. When it comes to ownership, founders often take on VC to grow their business into a viable company, thus giving up a stake. In addition, many share ownership with co-founders which can create even more division, making the requirement of 51% ownership an unrealistic demand. This, along with proof of an established network in Sweden and proof of sufficient funds, all add up to more conditions that exclude founders in early stages.

Results from The Local Expat Survey
A survey was carried out during April 2026 in collaboration with digital news publisher The Local and information services company Infostat to give a snapshot of expat life in Sweden today by surveying subscribers of The Local. Key findings will be shared throughout this section to illustrate the various decisions and experiences that impact talent attraction.
What is an expat? There are many interpretations of what defines an expat. In this report we refer to an expat as a legally working individual who temporarily resides in a country of which they are not a citizen, to pursue a career-related goal. Where expats differ from immigrants is generally their intention is to eventually return to their home country.
One in three expats work in tech
The following responses paint the picture of a group who are highly educated and are working within fields such as IT, tech, and data. This strengthens the view that Stockholm and Sweden in many cases attract a specific group of educated individuals who come here to work within the tech sector. It’s also worth noting that subscribers of The Local likely encompass a particular educated subset of society, leading to these kinds of responses.
Figure 9. What industry do you work in?
Figure 10. What is the highest level of education you have achieved?
Figure 11. What type of residency do you currently have in Sweden?
The competitive disadvantage
As shown in the previous section, Sweden’s current startup visa is neither competitive nor reflective of contemporary entrepreneurship today, both when it comes to its conditions and processing time. Of the 13 comparable countries in Figure 2.4, 11 offer a fast-track route specifically targeting startup founders and entrepreneurs. Two of those 11 stand out as potential models for Sweden to adopt, in the UK’s Innovator Founder visa and Denmark’s Startup Denmark scheme.
Inspiration abroad
The UK’s Innovator Founder visa (administered through Home Office–approved endorsing bodies) requires a new venture that meets three tests: it must address an identified gap in the market, be viable through a credible, realistic plan, and be scalable showing evidence of job creation and growth into national and international markets. Successful applicants receive a three-year permit and in addition must attend meetings with their endorsing body at the 12- and 24-month marks to demonstrate progress. The route is not necessarily easier; results must be delivered in order to continue, but it offers a transparent, fast path to getting started.
Startup Denmark is similar in spirit. To apply, you must have a business idea with demonstrable scalable growth potential, be a full or partial owner of the company, and play an active role in running it. As with the UK route, the process has two stages: first, an independent expert panel assesses the business plan (typically within six weeks); then, with an approved business plan, the applicant applies separately for a residence and work permit from the Danish Agency for International Recruitment and Integration (Styrelsen for International Rekruttering og Integration).
Several features distinguish these schemes from Sweden’s residence permit for self-employment:
-
Focus on innovation
Both the UK and Danish routes explicitly target new, innovative business ideas. Sweden’s system, while rooted in equal treatment, is arguably misdirected in not differentiating between business types. In practice, someone opening a restaurant, their own consultancy, or a retail shop are assessed in the same pool as someone building a scalable growth company.
-
Independent endorsement
Sweden does not offer endorsement by a qualified body that can vouch for an applicant’s track record or business concept. The UK and Denmark both rely on independent endorsing bodies or expert panels to assess business viability, making the criteria for a strong application far more transparent. In comparison, Sweden’s process is smoother administratively but offers little guidance on what constitutes a strong application, likely a key driver of its high rejection rate.
-
Capital requirements
Sweden requires roughly 11 times more capital upfront than the UK (SEK 200,000 versus SEK 17,800), before any additional costs for accompanying family. Sweden also requires significant industry and business experience alongside an established network of contacts and potential customers, neither of which is required by the UK or Denmark.
In short, while the UK visa has the most rigorous process, with ongoing accountability, it is fast and favours high-growth concepts, attracting ambitious founders. Denmark’s scheme on the other hand is the most transparent and allows co-founders to apply together. These kinds of targeted schemes start with a strong set of underlying requirements while also addressing the urgency of a founder’s time.
Three out of ten expats are already looking elsewhere
Further results from the expat survey reveals there is positive sentiment towards a specific fast-track visa programme with a third of respondents expressing interest and roughly another third recommending the visa to others. At the same time, three out of ten respondents would move to another country (in or outside the EU), while 60% cite uncertainty about residence permits as a reason for leaving Sweden. This shows that migration processes likely add to expat struggles and within industries such as tech, this can be critical as talent is much more mobile between countries if conditions are not right.
Figure 12. If Sweden introduced a startup visa programme (fast-tracked residence permits for entrepreneurs), how interested would you be in applying or recommending it to others?
Figure 13. Have you considered moving to another country specifically because they offer better support for foreign entrepreneurs?
Figure 14. If you're considering leaving or are unsure about staying, what are your main reasons?
Transitions that are too short
In addition to the lack of a startup visa, the system for transitioning between visa categories also compounds the problem. Pathways between statuses do exist on paper, but they are short, conditional, and poorly connected to the long-term routes that matter. The friction this creates falls hardest on exactly the people Sweden should most want to retain.
As of 2025 approximately 40 percent of Sweden’s doctoral candidates have a foreign background
While post-2021 migration law changes made it much harder for non-EU PhD graduates to remain, recent amendments as of June 2026 have loosened various rules with a now 3-year track to permanent residency (reduced from 4-7 years) and an increased 12–18-month post-graduation job-search permit period.[1]
The work-to-entrepreneurship track on one such grey area. Although the job-seeking permit nominally allows a graduate to ”explore the possibilities of starting a business,” founding one means being on the self-employment permit, a separate, first-time application carrying its own demanding conditions as detailed previously. Similarly, there is not always a straightforward progression from a work permit; for instance an employee who develops an idea and wants to build a company cannot simply move into a founder status, because no such bridge exists. Swedish do allow certain students and work-permit holders to apply for a new permit category from within Sweden. The policy problem is therefore not the complete absence of legal routes, but their conditions, predictability, processing times and practical continuity. The people with potential to become Stockholm’s next generation of founders, with local knowledge, networks, and credibility that make a venture likely to succeed and stay, therefore face a choice between abandoning the idea or leaving the country to pursue it elsewhere.
Taken together, these gaps describe a system that is leaking at both ends of the talent pipeline. It admits skilled people, allows them to accumulate exactly the experience and connections that make them valuable, and then provides no smooth route to convert that value into a long-term contribution for Sweden, whether as an employee progressing toward settlement or as a founder building a company. The transitions are not so much broken as poorly built to reach the other side.

The onboarding gap
If companies are successful at both attracting talent to Stockholm and getting their visa accepted, a third problem follows: getting the new arrival and their family genuinely established in Swedish society with a foundation solid enough that they stay. Attraction and admission are necessary but leave the job half done when retention is the next crucial hurdle decided in the first months on the ground. It is a make-or-break moment where Sweden risks losing talented people.
The core failure is the absence of structured relocation support. Sweden offers incoming international talent no single point of contact on arrival to streamline processes. Many companies offer support, but this is a unique perk to larger, often more international organisations that understand the difficulties of supporting foreign talent.
The one-stop shop option
Competing countries have managed to tackle some of these challenges with two strong examples in Denmark and the Netherlands. Denmark’s International Citizen Service notably co-locates all the relevant authorities in one place. This way a newcomer can complete the CPR (personal identity) number, tax card, health insurance card, and residence permit in a single sitting.
Operating in six cities, the services are free, and it extends beyond paperwork into career guidance, recognition of foreign professional qualifications, and in the Copenhagen region includes job programmes for the newcomer’s spouse.
The Netherlands runs the same style of programme at greater scale across eleven official expat centres where a single combined appointment settles both municipal registration and immigration formalities. The clear focus of this strategy is speed on the one document everything else depends on, the Dutch citizen service number, which is issued within about five working days through the centres, against up to thirty via the ordinary municipal route. Companies can also begin this procedure while the employee is still abroad, so the family completes several formalities in one visit.
No fast lane
Sweden offers incoming international talent no equivalent. In place of a coordinating institution there is a do-it-yourself model that in practice means assembling a personal identity number, a bank account, a BankID, school placements, and housing, each through a separate authority, on its own timeline, much of it in Swedish, with several steps locked in a sequencing problem where each prerequisite depends on the last. The personal number (personnummer) bottleneck is the clearest example. It gates the bank account and BankID yet has no fast lane of the kind Denmark and the Netherlands have deliberately built. A move that a competing city addresses in one guided appointment, Sweden leaves to the newcomer.
Support for spouses and partners is missing entirely, and this matters more than it first appears, simply because the trailing partner can be a strong predictor of whether a relocation succeeds. Foreign qualification recognition, language training, and job-seeking support for partners are not part of Sweden’s offer; competing countries provide them as standard. A senior hire whose partner cannot work, cannot requalify, and cannot find a foothold is a senior hire who leaves within two years, regardless of how good the job or the visa was.
The partner blind spot
Two frictions sit above all the others, raised repeatedly by Stockholm companies across every size and sector: housing and long-haul flight connectivity. On housing, the binding constraint is supply, not price. Affordability is real, around 60% of young people in Stockholm report difficulty finding affordable housing, but the deeper problem for an incoming professional is that suitable housing simply cannot be secured quickly through normal channels, regardless of budget. A relocating family with money to spend still cannot easily convert it into a place to live, and that is an attraction problem, not merely a cost-of-living one.
Long-haul connectivity tells a similar story from a different angle. Arlanda remains a capable European hub, but the intercontinental routes that matter most for recruiting senior talent and closing cross-border deals have thinned considerably. Arlanda has comparatively fewer direct links to the business centres global companies route through. Therefore, a candidate weighing Stockholm against London, Amsterdam, or Copenhagen will often find the practical question of how easily they can get home and back to headquarters, tilting against the city.
None of these gaps are impossible to close. Structured relocation support, partner integration, housing supply, and direct flights are all solved problems elsewhere; Sweden’s disadvantage is one of omission, not difficulty. A company can run a flawless recruitment process and clear a successful visa application and still watch the hire leave, because the city never gave the family a reason, or the realistic means to stay.
A great city to live in, a hard one to belong to
There is a clear difficulty identified within the expat survey when it comes to integration into Swedish society such as making friends, the language barriers and a sense of loneliness. It unfortunately seems challenging to feel a sense of belonging culturally if one is not part of it already somehow, for instance via a partner or other family member. However, Stockholm as a city to live in received an overwhelmingly positive recommendation, with the top reason for relocation being work. Again, this likely reflects the type of responent (i.e. The Local’s readership), but still emphasises the connection between a city’s liveability and job offerings.
Figure 15. What made you decide to move to Stockholm?
Figure 16. What has been your biggest challenge in settling into Swedish society?
Figure 17. How would you recommend Stockholm as a city to live in?
A promise half-vested
The baseline problem
Sweden’s ability to attract top talent depends in large part on having the right incentives in place. One area that warrants significant reform is the taxation system. Several improvements have been made in recent years to improve talent retention, such as reforms in the expert and R&D tax relief schemes. However, other improvements are still necessary. Sweden’s marginal tax rate on high incomes ranks among the highest in the OECD, a fact that risks deterring highly skilled individuals from relocating to Sweden.9 Furthermore, the disparity between the taxation of labour income and capital income has necessitated complex regulatory frameworks at the corporate level, most notably the 3:12 rules. The complex situation warrants comprehensive tax review with particular emphasis on enhancing the competitiveness of the Swedish tax system in attracting top-tier talent.
What is the R&D tax relief scheme?
Companies can reduce their employer social security contributions by up to 20% on salaries for employees engaged in qualifying R&D work.
What is the expert tax relief scheme?
Qualifying foreign experts, researchers, and key personnel can exclude 25% of their income from tax and social contributions for up to 7 years.
However, attracting talent can come in other compensation-driven forms. One that is particularly powerful for startups and scaleups competing against higher salaries and across a global market is offering equity and ownership. Stock-based incentive programmes are a key tool in attracting talent by making employees co-owners, strengthening their loyalty to the company and driving innovation. High-growth startups are demanding and risky, which is why offering stock options can make a significant difference in return on investment for talent looking to join.
In Sweden there are various equity and ownership incentive schemes that startups can take advantage of:
-
Employee Stock Options (Personaloptioner)
Regulated within the Income Tax Act (Inkomstskattelagen), this scheme is taxed when exercised as employment income at up to 50-55%, and at sale as capital gains (25-30%).
-
Qualified Employee Stock Options, QESO (Kvalificerade personaloptioner)
Regulated within the Income Tax Act, gains in this scheme are untaxed at exercise, and taxed only on sale as capital gains (25-30%) outside the 3:12 rules, though most most recipients fall under 3:12, where gains below the dividend allowance are at taxed at 20% and above at employment incomes rates up to 58%.
-
Warrants (teckningsoptioner)
A standardised financial instrument bought at fair market value by the employee.
Because warrants need to be acquired at fair market value to avoid employment income taxation, they can be very expensive for the employee as well as administratively demanding for the company since they require approval from the company’s board and the Swedish Companies Registration Office. Similarly, regular employee stock options are also not a competitive option since they are taxed twice, first as employment income, which the company must also pay social security contributions on, and second as capital gains when shares are sold. Therefore, for the purposes of this report we will focus on Qualified Employee Stock Options (QESO), which is the strongest incentive programme of the three and has the most potential if adjusted to meet the characteristics and needs of high-growth companies today.
The ins and outs of QESOs
QESOs are an important tool for startups to stay competitive in the global market, by offering company ownership which falls under capital gains tax on returns made rather than employment income tax. Companies benefit from these kinds of schemes where they can offer share options for free while at the same time reducing the amount they must pay towards social security contributions, compared to traditional compensation methods such as higher salaries. Launched in 2018, this legislation gave startups an easier method of recruitment for key employees in early stages of company development. An expansion in 2022 further allowed QESOs to be issued to board members, which helped accelerate retention of competent boards for smaller and newly started companies.
At face value, the overall purpose of QESOs is very good and comparable with international alternatives. They genuinely strengthen an offer avoiding unnecessary taxes from both an employee and a company point of view with no taxation until the point of sale of shares and no employer social security contributions. However, as time has gone on the parameters of QESOs have become too rigid, narrow, and administratively fragile due to changing market dynamics. High-growth companies quickly surpass size requirements and at the same time small companies do not have the administrative resources or awareness to take advantage of the scheme. Currently, companies who can utilise QESOs must meet the following requirements:
-
1
Be younger than 10 years old
-
2
Have fewer than 150 employees
-
3
Have annual turnover or balance sheet total below SEK 280M
Data from Dealroom reveals that of all startups and scaleups founded in Stockholm County in the last 10 years, 9% are ineligible for QESOs due to their employee count and or their most recent revenue year passing the limits imposed. However, those 9% represent 92% of the total revenue generated for the latest year, as well as 60% of all jobs created in the ecosystem. This means that once a company succeeds and scales, they are automatically no longer eligible for this incentive which should be continuing to make them more competitive on a global market.
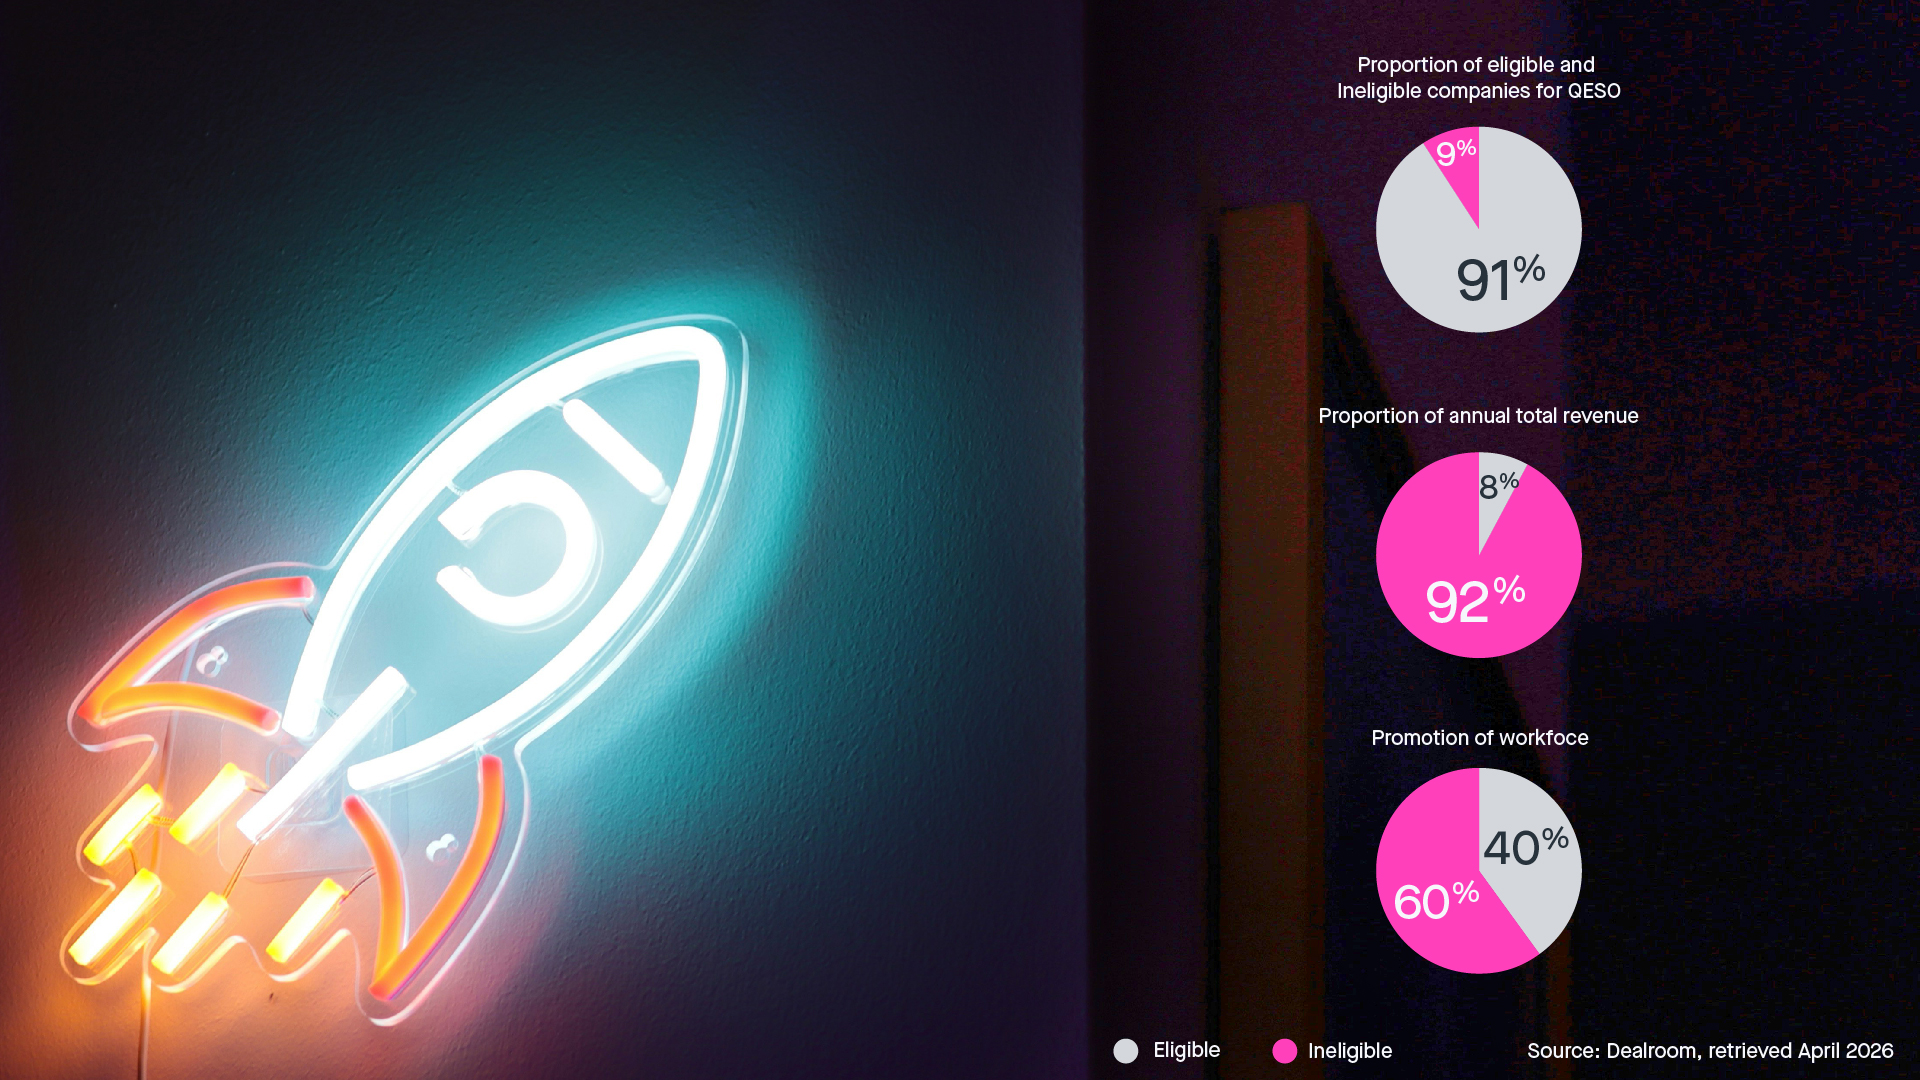
At the other end of the spectrum data from the Swedish Tax Agency shows that within Stockholm County only 15 companies took advantage of the QESO scheme in 2025. If we compare this with the 970 companies eligible on Dealroom that’s only 1.6% of the ecosystem.
This low uptake in practice could be interpreted in several ways. One, that young, small companies lack the resources or advisory support to implement QESOs. This would include resources such as in-house legal or tax counsel that would be able to handle the bureaucratic set up needed. Another possibility is the lack of knowledge that it exists, since it is not promoted as widely as perhaps it should be.
Figure 18. Number of unique companies that have taken advantage of QESO in Stockholm County
Companies having used the Qualified Employee Stock Options programme (QESO)
Source: The Swedish Tax Agency
In addition to problems with the requirements and subsequent uptake, there is a mandatory 3-year vesting cliff, a personal cap of SEK 3M in vested shares, and a company cap on the total value of shares issued at SEK 75M. In practice, this means that if an employee leaves the company before three years have passed unvested options are forfeited, and if they are to stay beyond 3 years when they go to exercise their options the share value is capped at SEK 3M. Company-wide, this means a maximum of 25 employees could take full advantage of the scheme if each were granted vested shares up to the personal limit of SEK 3M. Of course this could be spread thinner among more employees, but it becomes less and less attractive when seekint to bring in highly-skilled, key individuals. This company cap of SEK 75M on total options issued is one of the first limitations that high-growth companies encounter when utlising the QESO scheme.
Competing at a higher level
Incentives like this can make the difference between someone choosing a job in Stockholm instead of elsewhere. Sweden’s QESO scheme is already the strongest in the Nordics, but now more than ever we are competing less with our Nordic neighbours and more with bigger players such as the UK, France, and the US. A great example is the UK’s Enterprise Management Incentive (EMI) scheme, which is one of the most globally competitive and has expanded eligibility significantly over the years to meet demands of high-growth companies. As of April 2026, the EMI has become available to companies with up to 500 employees with gross assets of £120 million (SEK 1.5B). This is roughly five times the size of Sweden’s cap of 150 employees and SEK 280M net turnover. In the UK, options are also taxed through capital gains, however at a lower rate of 18% as of April 2026, compared to Sweden’s 25%. These differences are what set countries apart and signal that they are places open for innovation and business.
The last mile problem
Early-stage strength, late-stage gap
Part of creating the right conditions for new companies to innovate and grow, aside from attracting and keeping talent, is having sufficient capital. This becomes important as companies expand beyond Stockholm and Europe, most notably into the US where there are strong sector ties in tech. Stockholm excels in early-stage funding, from pre-seed through Series A, notably outperforming most European peers. As previously mentioned, Stockholm ranks third in Europe for VC raised over the last year, giving the city a strong position with opportunity for more growth.
| Metro region | Venture capital raised (SEK billion) |
|---|---|
| London | 251.1 |
| Paris | 81.4 |
| Stockholm | 40.2 |
| Munich | 31.6 |
| Berlin/Brandenburg | 30.6 |
| Cambridge (UK) | 28.7 |
| Helsinki | 18.2 |
| Amsterdam | 16.3 |
| Copenhagen | 13.4 |
| Barcelona | 12.5 |
Source: Dealroom, 2026
This strength is underpinned by a generation of Stockholm-founded funds that have built global reputations, including Creandum and EQT. The founder-to-angel pathway is another defining feature, reinforced both by physical proximity and by a 2003 tax rule (näringsbetingade andelar) that allows founders who exit a company to roll the full, untaxed proceeds into new investments through their holding company. The result is an unusually deep pool of experienced founder-turned-angels coming out of Spotify, Klarna, iZettle and others. The ”Spotify mafia” alone has gone on to found, fund or run many of the most ambitious startups Stockholm has produced, including Lovable, whose backers also include Klarna founder Sebastian Siemiatkowski’s Flat Capital.
The gap opens at Series B and beyond, where companies enter the so-called ”valley of death” between exhausting their initial funding and attracting larger institutional rounds, typically in the SEK 0.2–1.1 billion range and upwards. This is not purely a Swedish problem, it is felt across Europe, but it has become especially acute in the Stockholm ecosystem, where the capital required to scale is increasingly difficult to source from the local market alone. Founders instead look abroad, most often to the US, where pockets are deeper and the appetite for risk is higher. Bringing in funding from abroad is not a problem in itself, the US in particular, can be a strong tool when it comes to scaling. If a company can secure American venture capital and prove itself in the local market it can be an important stepping stone that leads into other markets.
Yet the consequences of shifting focus to new markets are not abstract. Spotify chose the New York Stock Exchange (NYSE) for its 2018 listing, while maintaining a strong cultural and operational presence in Stockholm. Klarna’s 2025 IPO also landed on the NYSE rather than Nasdaq Stockholm. These choices illustrate how global capital markets can gradually shift parts of a company’s centre of gravity abroad, influencing where future investment, senior talent, strategic functions and tax revenues ultimately accrue. For a small country like Sweden, maintaining strong links to its most successful companies as they scale globally is therefore of significant economic importance.
Deep tech, shallow funds
Nowhere is this gap more visible than in deep tech. Stockholm ranks 13th globally and 5th in Europe among deep tech hubs and continues to lead Europe in per-capita deep tech VC investment over the 2020–2025 period. Yet beneath the headline ranking Stockholm’s deep tech funding has fallen 82% between 2020 and 2025, the steepest decline of any European hub10.
This is a structural mismatch rather than a loss of innovation capacity. Sweden continues to produce world-class deep tech founders through its leading universities, research institutes and unicorn alumni networks, which collectively generate a strong pipeline of science-based startups. The challenge is the absence of strong public co-investment infrastructure to carry these companies through the capital-intensive scale-up phase. While Sweden’s innovation agency Vinnova provides solid early-stage innovation funding (around SEK 3.5 billion annually, broadly comparable per capita to Innovate UK), Sweden lacks a dedicated growth-stage vehicle for deep tech. Germany’s DeepTech & Climate Fund operates with €1 billion (SEK 10B) under management to anchor growth-stage rounds, and France’s Bpifrance deployed more than €5 billion (SEK 50B) across over 5,500 companies in 2024 alone, through a single agency that combines grants with equity at scale. Sweden has no equivalent, and Vinnova’s deep tech fund is capped at SEK 4 million per company, which suits seed-stage validation but cannot anchor the SEK 0.2–1.1 billion rounds that capital-intensive deep tech companies need to scale at home.
EU-level instruments such as the European Investment Bank and the European Innovation Council do reach Swedish companies, but they are not designed to anchor large national rounds or to keep companies headquartered domestically. They complement national institutions rather than replace them, and Sweden’s peers have moved decisively to fill this gap at the national level. It is worth noting that Sweden’s own EQT has been selected as the preferred investment advisor and fund manager for the Scaleup Europe Fund, which is the cornerstone of the EU Startup and Scaleup Strategy and the largest of its kind ever mobilised in Europe. This gives a clear signal that Swedish investment organisations are trusted and capable of handling Europe-wide funding.
Some will object that Sweden has recently strengthened its public commitment to research and innovation. The December 2024 research and innovation bill, framed by the government as the largest in Sweden’s history, increased annual funding for research and innovation by SEK 6.5 billion by 2028, including around SEK 1.2 billion annually for the new Clusters of Excellence programme when fully implemented in 2028. These are welcome additions and reflect a serious political recognition of the issue. However, two qualifications limit their relevance to the scale-up gap. First, the bill is overwhelmingly weighted toward research excellence, university-based science and applied collaboration, rather than toward the equity instruments that growth-stage deep tech companies need. Second, the missing piece is a national body capable of writing the SEK 0.2–1.1 billion cheques into capital-intensive Swedish scale-ups, which the 2024 bill does not provide. Without that, the strongest Swedish deep tech companies will continue to take growth-stage capital, and often their headquarters, abroad.
The missing institutional investor
A state fund is not the only way to close the scale-up gap, and arguably not the first place to look. The deeper question is why private capital does not fill it. Here Sweden shares a structural weakness with the rest of Europe: its largest pools of long-term capital, found in pension funds and insurers, allocate comparatively little to venture and growth equity. In the United States, public and private pension funds have been cornerstone investors in venture capital for decades, and that steady institutional money is part of why American growth-stage rounds are both larger and more readily available. European institutions, bound by more conservative mandates and risk frameworks, have historically opted out of this route.
Sweden is not exempt. Its public pension buffer funds (the AP funds) and large insurers manage substantial long-term assets, but their exposure to domestic venture and growth-stage technology is modest relative to the scale of capital they hold. The consequence is that the SEK 0.2–1.1 billion rounds a scaling deep tech company needs cannot be assembled domestically. Not because the money does not exist in Sweden, but because it is not mandated, incentivised or structured to flow there.
The ”valley of death” therefore becomes not only a shortage of capital, but a misallocation of it. In a country such as Sweden with deep savings and a sophisticated financial sector this means that those savings are unable to flow into its own most promising companies. Any long-term solution must address that channel, not merely add public money alongside it.
Closing the last mile
If the gap is both a shortage of public co-investment and a misallocation of private capital, the response must work from multiple angles.
The first is a dedicated growth-stage vehicle for capital-intensive companies. This means something like a national body, referenced earlier, that is capable of writing billion-krona cheques, taking a company to the next level. For Sweden this could look like a single agency combining grants with equity, a mandate explicit enough to anchor large rounds with the scale to lead rather than merely follow. Such a vehicle could be built as an expansion of Vinnova’s mandate or as a separate institution; what matters is that it operates at growth-stage scale, which Vinnova’s current SEK 4 million per company cap does not.
The second is to mobilise private capital rather than substitute for it, working on both the supply of institutional money and the structures that channel it. On the supply side this could look like a public vehicle that anchors funding rounds and co-invests alongside private funds, taking early risk to then drawing in pension funds, insurers and international investors, multiplies the effect of every public krona and builds the domestic growth-stage market the ecosystem currently lacks. The aim is not a permanent state shareholder but a catalyst that makes the next round investable. On the structural side, Swedish pension and insurance capital are as much part of the solution as any new agency. The 2025 reform of the buffer-fund system, which consolidated AP6’s private-equity expertise into AP2, is the natural moment to build a domestic growth-stage focus into the mandate rather than leaving allocation to drift abroad. Unlocking even a small reallocation of long-term domestic savings would dwarf what any single public fund could deploy.
None of this requires Sweden to abandon what already works. Its early-stage strength, its founder-to-angel pipeline and its world-class research base remain genuine advantages. The task now is to carry companies through the one stage where the system currently fails them.
It is also worth ending on what makes Sweden well placed to take these risks. The country’s welfare system provides something its peers cannot easily replicate in a functioning safety net beneath the people who take entrepreneurial risk. Those who join an early-stage company or invest a large share of their savings in one do so knowing that failure will not leave them destitute. That security is a quiet but real asset lowering the personal cost of risk-taking across the whole ecosystem. The missing piece is not the willingness to take risk; Sweden’s institutions already underwrite that. The missing piece is the capital to reward it at scale, and to keep the headquarters, the talent, the tax base and the next generation of founders and funders in Sweden.
Interview: Finding the right mix
Erik Lindblad, Founding General Partner, Inception Fund
You invest in companies at their inception. What kinds of funding challenges do you see for those companies as they move beyond the early stages and look to scale?
For technically strong teams with strong business performance building within AI there is right now an abundance of capital. But the capital concentration is also greater than ever, all funding goes to the very best and if you are not a part of that percentile it becomes difficult to get any funding at all. At the later stages, Europe still lacks adequate growth funding. The new EU Growth fund of €5 billion managed by EQT is a great improvement to the ecosystem, but much more is needed.
How early in the process do Swedish companies start looking abroad? Is it a given that the first port of call is the US?
If you are building a venture backed business you have to build with a global mindset from day one, especially when starting in Sweden that is such a finite domestic market. To most, the US is and, in many cases, should be the first port of call. If you are selling business facing AI solutions and or building AI infrastructure, the market is much more ready to buy, and if you win the US, the rest of the globe will follow. For many, it’s also central to get exposure to the US VC funds for later stage funding, and in most cases, they require that you show successful scaling in the US.
Do you find it problematic that Sweden doesn’t have as strong of a market for late-stage financing?
Of course, we need much more domestic funding. It’s not an option to fund a full journey locally today. But it’s also a bit naive to think that we should be fully independent here as a small market, we should collaborate with the best globally and build for the global maximum. It’s about finding the right mix of both.
What needs to be done?
Reform 1: Fast-track the talent pipeline
-
A dedicated startup visa that reflects the realities of entrepreneurship
Greater internationalisation requires simple and predictable rules for labour migration. Therefore, the centrepiece of this reform is a dedicated startup and entrepreneur visa, covering both founders and the talent they need to hire. Sweden’s current residence permit for self-employment averages 16 months; the goal should be to bring a new scheme to within a two-to-three-week range, making it genuinely competitive rather than nominally improved.
Speed alone is not enough, and the current visa’s conditions do not reflect how startups are built today. The 51% ownership requirement excludes any founder who has taken on VC funding or shares equity with co-founders, which describes most high-growth ventures. Proof of an established customer network in Sweden locks out early-stage founders before they’ve had the chance to build one. Capital requirements are immense in comparison to other countries, and prior business experience is a blunt filter that rules out first-time founders with strong, venture-scale ideas.
A redesigned visa should replace these conditions with an assessment of business viability: is the concept innovative, is the plan credible, and does it have genuine potential to create jobs and grow? This assessment should ideally be carried out by an independent industry expert committee rather than left to the Migration Agency alone. A panel with real startup and investment expertise is better placed to distinguish genuine venture-scale potential from applications that do not meet the bar, which should also address the current 7% acceptance rate on the residence permit for self-employment. The goal is not simply to approve more applications but to make better decisions, faster, with greater transparency about what a strong application looks like. -
Smoother transition between visas
The bottleneck is not only at the point of entry. Sweden also loses talent at the transition between visa categories, and a credible reform package needs to address both.
Two transitions in particular need fixing:
Study-to-work: International PhD graduates and students who complete their degrees in Sweden can already apply for a work permit without leaving the country, but the transition should be made faster, simpler and more predictable. Sweden has already invested in their education; the current system should make it as easy as possible to retain that investment. Aligning with the EU Blue Card framework where possible would also reduce administrative burden for the most mobile, most in-demand applicants.
Work-to-entrepreneurship: Employees already in Sweden on work permits who want to found a company can in certain circumstances apply for a self-employment residence permit without leaving Sweden, but the route should be made clearer, faster and better suited to founders. The people most likely to become Stockholm’s next generation of founders are often already here, working in its fastest-growing companies.
-
Integration to build lasting impact
Attracting someone to Stockholm is only the first part of the challenge. If the first months in the city are disorienting and administratively burdensome, the risk of losing that talent within a few years rises sharply. Sweden currently has no structured relocation support for incoming international talent. The model worth adopting is a single coordinated service, similar to Denmark’s International Citizen Service or the Netherlands’ expat centres, covering visa processing, tax registration, and national ID in one place; school placements, banking setup, and housing guidance; and qualification recognition, language training, and job-seeker support for partners and families.
Competing countries provide this as standard. Sweden does not, and the gap is often the deciding factor in whether an international hire stays beyond two years. The target should be to make the first 90 days in Stockholm as smooth as the relocation packages Silicon Valley companies routinely offer. Similarly, if Stockholm is to become an even more natural choice, the lack of housing and flight connectivity must be addressed: these remain two of the city’s biggest ongoing problems for attractiveness and competitiveness.
Reform 2: Make equity compensation work
-
Modernise Sweden’s most promising incentive scheme with three targeted changes
Sweden’s Qualified Employee Stock Option scheme, known as QESO, is the strongest equity incentive available to startups in the Nordics. However, the companies that need it most are increasingly the ones it excludes. Dealroom data shows that of all Stockholm-headquartered startups and scaleups founded in the last ten years, only 9% are ineligible for QESO. Those 9% represent 92% of ecosystem turnover and 60% of all jobs created. If QESO is the primary tool for attracting and retaining talent in high-growth companies, it cannot be designed to exclude the highest performers.
The problem is not only eligibility. The Swedish Tax Agency data shows a steep decline in the number of companies using the scheme in recent years, even among those that qualify. This signals a fundamental design flaw: the scheme is both too narrow for the companies that need it and too administratively fragile for those that could use it. The reforms below are focused and implementable within this or the next parliamentary term. They do not require reinventing the scheme, only updating it to reflect the scale and ambition of today’s high-growth companies.
-
Invest in the employee
Under the current structure, an employee who leaves within three years receives nothing; Those who stay are limited to a per-person cap of SEK 3M. These limitations can be a deterrent for senior international hires who are weighing Stockholm against offers elsewhere with more flexible vesting.
Two key changes will make an offer more appealing:
Changing the cliff period: By decreasing the 3-year cliff to a 1-year cliff with a 4-year total vesting period, Sweden’s QESO will be more in line with equivalent international schemes, making Sweden’s offer more competitive.
Raising the per-person cap: Increasing the cap on share options exercised from SEK 3M to at least SEK 6-10M will add to a meaningful offer for the senior international hires that scale-ups need most.
-
Expand company eligibility
The current limits do not reflect the scale of the tech-driven growth companies we see emerging today. The limits of fewer than 150 employees and working shareholders, SEK 280M in net turnover or balance sheet total, and company caps of SEK 75M on total options issued must be updated.
Each of these needs updating:
Raise the employee cap: Increasing the cap on employees from 150 to at least 500, will match the UK’s Enterprise Management Incentive scheme as of April 2026.
Raise or remove the company-size threshold: Sweden’s SEK 280M net turnover or balance sheet total threshold compares poorly with the UK’s £120M gross assets threshold, which is approximately six times more generous in practice.
Raise or remove the SEK 75M company cap: This restriction cuts off growing companies at exactly the moment they need to compete hardest for talent. An ambitious route would be to drop the cap all together, letting companies themselves set their own limits.
Beyond these three concrete changes it’s also worth considering expanding eligibility beyond the 10-year limit and to include fintech and financial services companies, both of which are currently excluded.
Reform 3: Unlock capital at the scale-up stage
-
Steer Swedish pension capital toward domestic growth companies
Sweden’s pension system already holds substantial capital, and part of it has private-equity expertise. AP6, the buffer fund set up in 1996 for this purpose, had grown to roughly SEK 77 billion by the end of 2024. However, most of that money has gone into buyouts (helping established companies change hands), not venture and growth investing (funding younger, high-growth companies). And of the little that has gone into venture and growth, most went to the United States rather than staying in Sweden. In short, the vehicle exists, but a domestic growth-stage mandate does not.
The 2025 reform of the buffer-fund system is the natural moment to fix this. It merged AP6’s private-equity expertise into AP2 and consolidated the other buffer funds. Rather than trying to amend a structure the reform has already replaced, the priority should be giving the reformed system a clear domestic mandate.
AP2 now holds the pension system’s private-equity capability and could be given explicit instruction to invest a modest 1–2% of relevant assets in Swedish growth-stage companies, either indirectly through other investment funds or directly alongside other investors. Including the former AP6 portfolio, AP2 is responsible for roughly SEK 550 billion in assets, and even this modest share would direct an estimated SEK 5–10 billion toward Swedish scale-ups. It’s a small percentage, but a meaningful sum that would be enough to anchor or co-anchor many SEK 0.2–1.1 billion growth rounds, keeping Swedish pension capital invested at home.
-
Strengthen government-financed pathways through a national scale-up fund
Sweden’s tech sector as a whole struggles to raise scale-up capital, but the challenge is most acute in deep tech and industry-heavy tech. This is a growing area for Sweden and in order to compete with leading tech hubs, it needs more pathways to financing, as France, the UK, and Germany have built through state-backed innovation funds.
One way forward is to establish a national scale-up fund, housed under the Ministry of Finance but operating independently, with a mandate to invest at Series B and beyond. The Swedish government is already working towards this with a new investigation launched in June 2026 to take the next step in strengthening Sweden’s position as a leading innovation country and better access capital for groundbreaking innovation and deep tech11.
A call to action
Stockholm is ready to take the next step. A great deal of work is already underway, the ecosystem is producing results that the rest of Europe has noticed, and the overall momentum is positive. The task now is to build on that momentum, championing what Stockholm has to offer, and removing the barriers that have the potential to hold it back.
Sweden’s soft power is one of its most underrated assets, and in the current global climate it may be the most important card the country holds. As institutional trust erodes in much of the world, Sweden’s stability, transparency and rule of law stand out. The country consistently ranks among the most liveable in the world for cleanliness, strong public services, generous parental leave, and a culture that is genuinely open and internationally minded. English is spoken fluently across the professional world, making Sweden far more accessible to international talent than its non-English-speaking peers. For those weighing up where to build a career or a company, the cost of living is substantially lower than in Silicon Valley, while the quality of work, particularly in AI and deep tech, is directly comparable. That reputation is a rare form of credibility, and it translates directly into open doors: for founders raising capital, and for companies recruiting globally.
As global instability persists, the timing has never been better for Europe, and for Sweden, to step into the gap. US-based scientists submitted 32% more applications for jobs abroad in the first quarter of 2025 than in the same period a year earlier.12 In March alone, US views of overseas job postings rose 68%. A wave of internationally mobile talent is, for the first time in a generation, looking seriously at Europe. The EU has taken note of this and put real money behind the moment with €500 million committed in May 2025 to its ”Choose Europe for Science” initiative. The response has been swift, with France, Germany and Austria already running active programmes aimed at US talent. Stockholm has the brand, the ecosystem and the quality of life to compete amongst the top countries but competing requires targeted efforts in actively marketing the city as a place that is genuinely open for business, not merely an attractive place to live. There are already signs this can work as Stockholm pulls ahead as Europe’s most attractive market for IPOs in 2025, a positive signal worth reinforcing.
The foundations for that message are already in place. Lovable and Legora have shown that world-leading AI companies can be built in Stockholm, and the attention they have drawn is itself an opportunity. At the same time Spotify and Klarna alumni networks are actively reinvesting in the next generation of founders, creating a self-reinforcing cycle of capital, mentorship and ambition.
None of this requires Sweden to reinvent itself. The fundamentals are strong, the reputation is earned, and the ecosystem is real. What it requires is speed and the removal of the policy bottlenecks that are, right now potentially turning away the founders, engineers and scale-ups Stockholm needs to reach its next level. This window of opportunity will not stay open forever. The mobile talent looking at Europe today will settle somewhere, and the cities that have already anticipated the need and changed their rules to meet it are the ones that will come out on top. Stockholm is entering its next unicorn era, and we must meet the moment to reap the benefits.
Interview: The Swedish success story isn’t finished
Arba Kokalari, Member of the European Parliament
As one of the EU’s leading voices for tech and digital policy, you’ve been vocal about Sweden being a frontrunner in AI and innovation. What is it about Stockholm, in your opinion, that sets it apart from the rest of Europe?
“Stockholm has the talent, the capital and one of Europe’s strongest startup ecosystems. Add to that a deep retail investment culture, solid digital infrastructure and a society with high trust in technology. Stockholm has a combination no other European city can match.”
What’s happening in Stockholm right now, in 2026, that makes you most optimistic?
“What excites me most is the ecosystem itself. Every generation of founders inspires, mentors, and funds the next. The kids who grew up watching Spotify and Klarna are now building Lovable and Legora. That flywheel is accelerating and somewhere in Stockholm right now, the next great company is being built.”
Looking 5-10 years ahead what do you hope for Stockholm and Sweden?
“I want Stockholm to be a city where anyone, whether they are building a company or pursuing a career, feels they can fulfil their potential. A place where Europe’s most ambitious entrepreneurs choose to stay, global talent wants to come, and opportunity is not reserved for the few. As a politician, my job is to make that possible: simpler rules, smarter incentives and an open door for the people who want to build here. The Swedish success story isn’t finished.
Author

Photos:
Mostphotos, Unsplash, Stockholmskällan, Mathieu Cugnot, Erik Lindblad